Brazil faces more challenging global backdrop in 2027, UBS says - Valor International
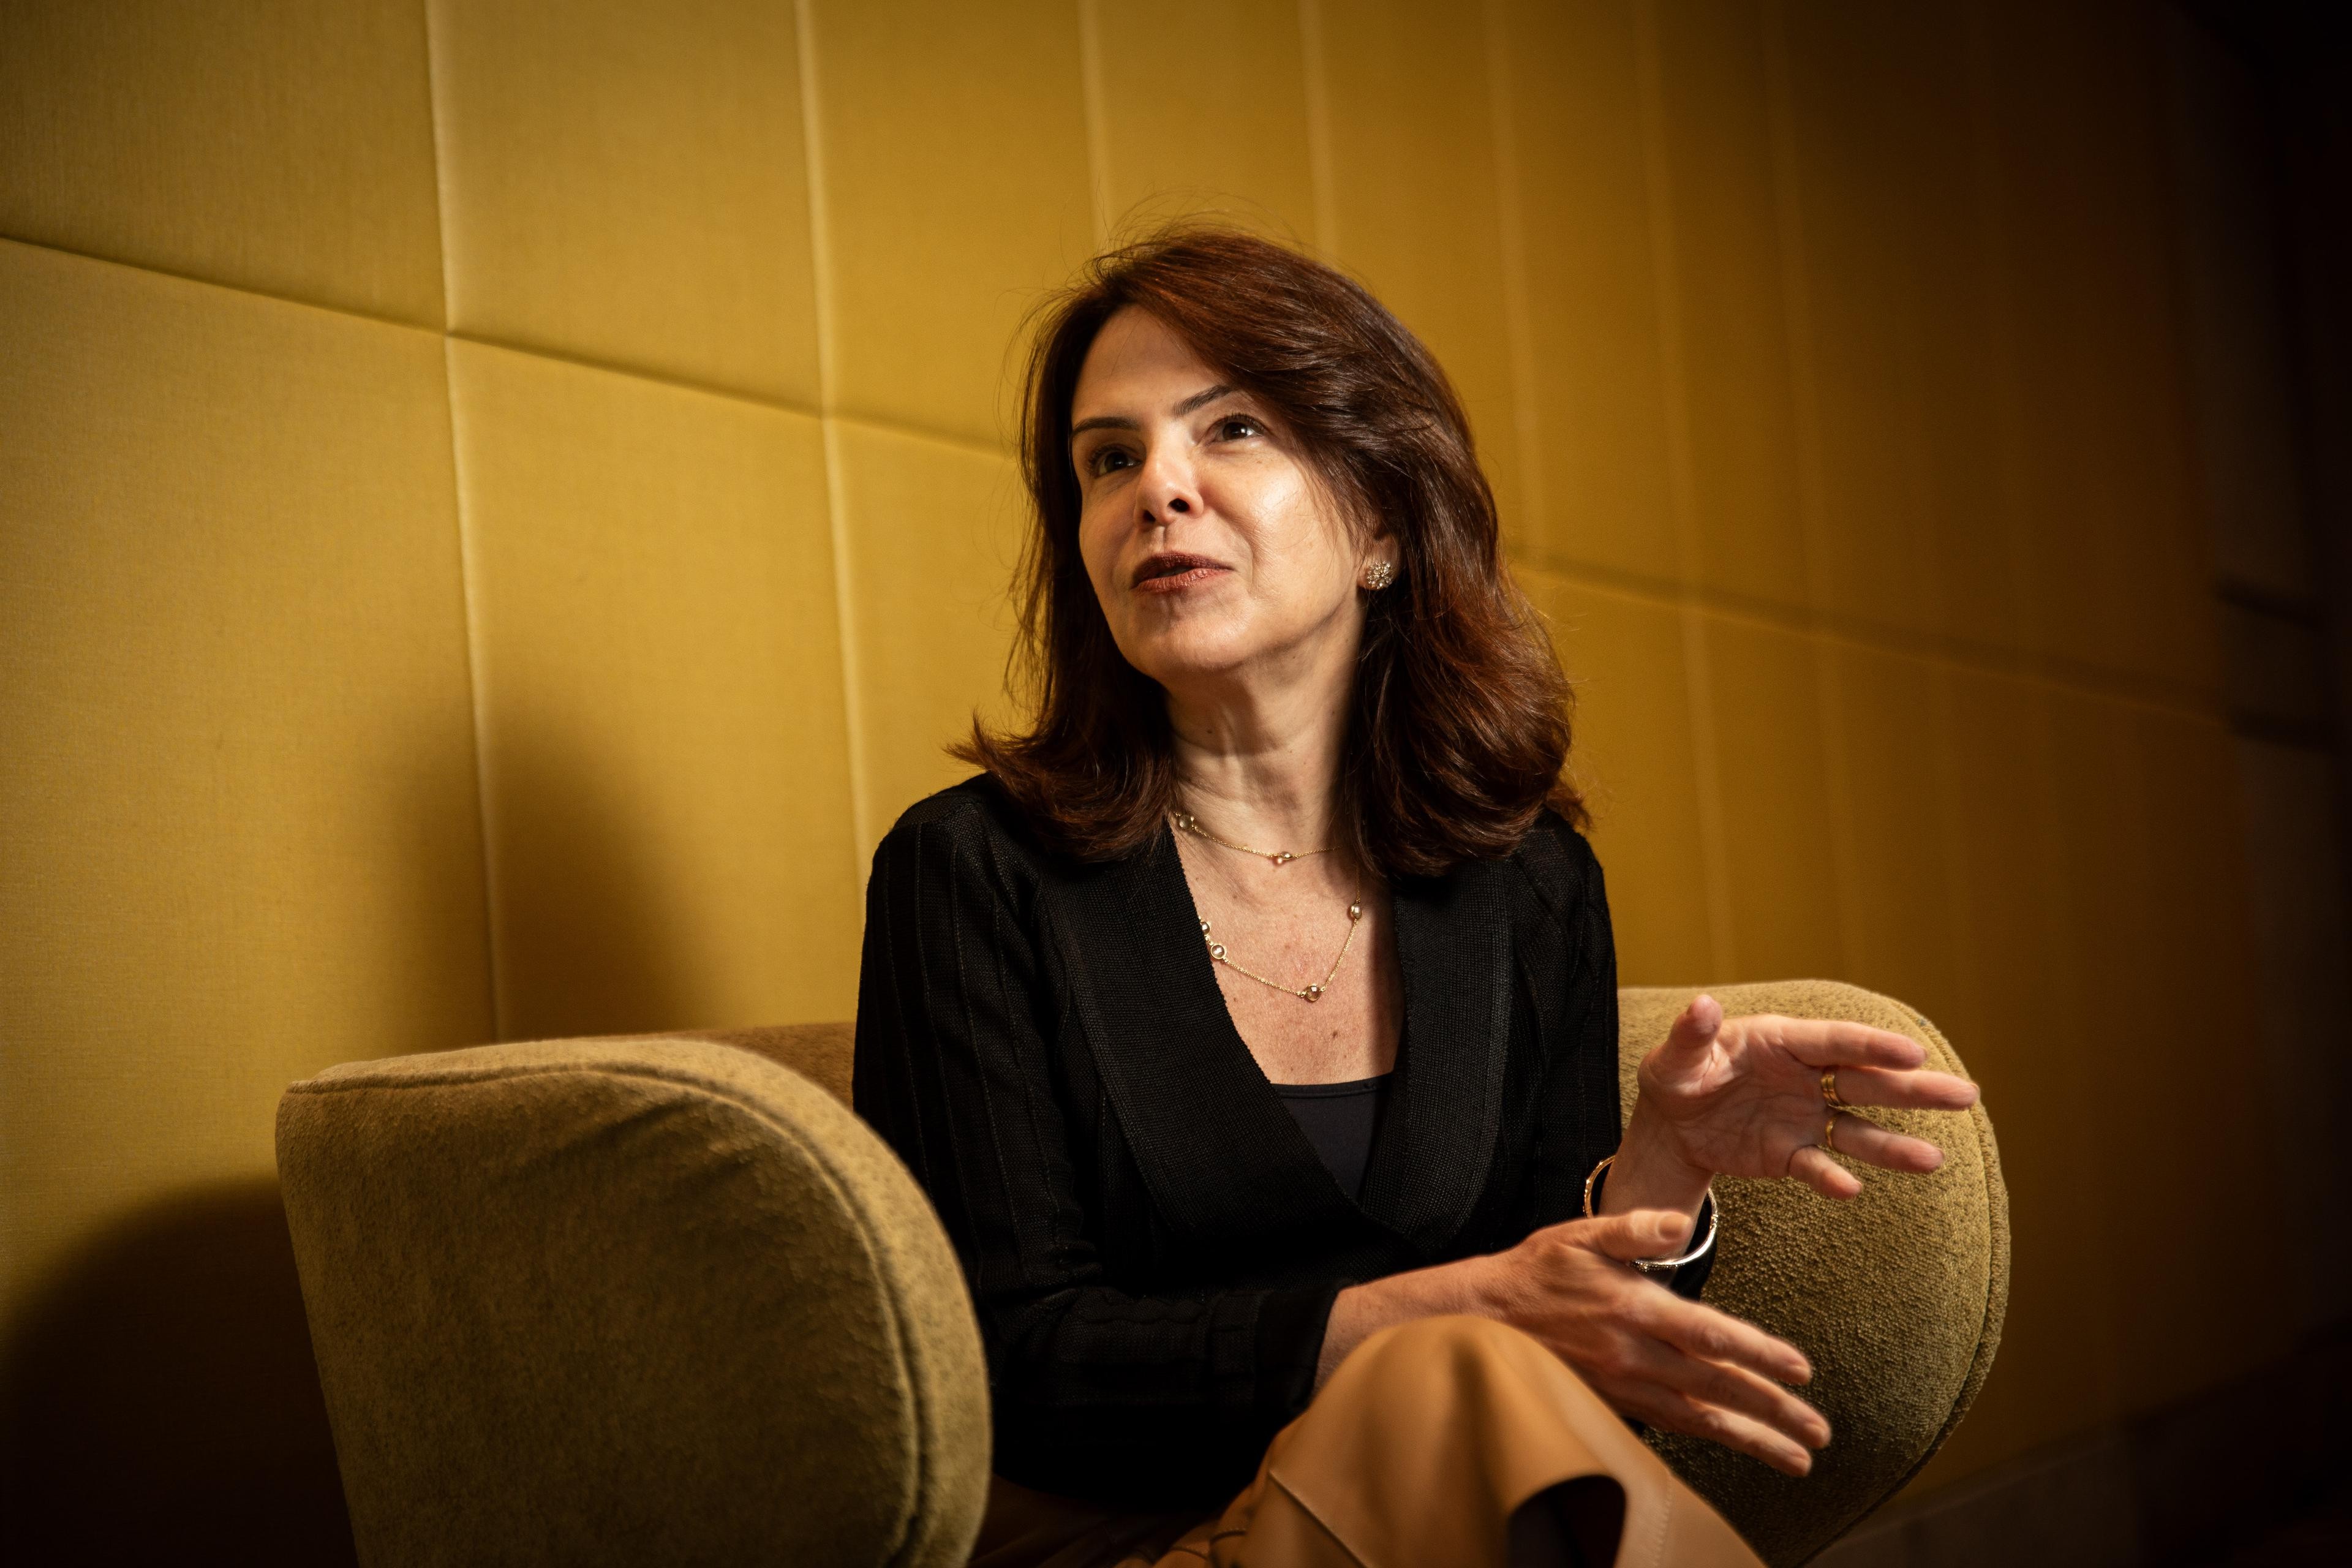
After a period in which elevated global interest rates, persistent inflation and geopolitical tensions coexisted without severely disrupting asset prices, mounting risks call for a more selective investment approach in 2027, said Solange Srour, head of Brazil macroeconomics at UBS Global Wealth Management (GWM), who recently also took charge of its investment division.
Emerging markets have benefited in recent years from global portfolio diversification and a weakening dollar. Those capital flows could dry up in 2027 if U.S. inflation proves persistent and forces the Federal Reserve to raise interest rates. Without exceptionally favorable external conditions, Brazil would lose a cushion that has helped mask its domestic vulnerabilities.
“Much of Brazil’s improvement, when the exchange rate went from R$6.30 per dollar in late 2024 to just over R$5, was driven by global rather than domestic factors. And we don’t think that tailwind will be there anymore,” Srour said in her first interview since taking on the dual role.
“The urgency of fiscal adjustment and restoring the three pillars of macroeconomic policy increases when external conditions are no longer extremely favorable. They don’t even have to be unfavorable. I just think that an environment less supportive than in the past already makes the need for action here more pressing.”
Srour said the fiscal proposal under discussion within the government had disappointed expectations, falling well short of the adjustment needed in a country with public debt at 84% of GDP and spending growing by around 5% to 5.5%.
She criticized the idea of focusing solely on limiting expenditures exempt from the spending cap or using a fiscal target as an anchor. Such an approach would only work if the target were sufficient to stabilize public debt; otherwise, “it won’t accomplish anything.”
In its Year Ahead 2027 report, which outlines global investment scenarios and strategies, UBS Global Wealth Management recommends exposure to emerging-market currencies through carry trades, highlighting the Brazilian real alongside the Mexican peso, South African rand and Indian rupee.
Ronaldo Patah, head of investment strategy for Brazil at UBS GWM, explained that such trades seek to profit from interest rate differentials between currencies in low- and high-yielding economies. The strategy is not a bet on the real’s appreciation.
Patah said UBS had downgraded its global equity outlook to “neutral” from “attractive,” making the same adjustment to its emerging-market rating.
“Brazil is part of emerging markets, and we know it relies heavily on foreign inflows, particularly in the equity market. That reduces the likelihood of attracting foreign capital, regardless of what’s happening domestically. The more challenging global backdrop alone makes positive inflows into the country less likely.”
Another channel through which global conditions affect Brazil is the pressure exerted by long-term U.S. interest rates. Under UBS’s more favorable base-case scenario, 10-year Treasury yields are projected to reach 4.75% in 2027. In its stress scenario, they could climb to 5.50%.
Such levels put a floor under long-term Brazilian interest rates, Patah noted. Compounding the problem, Brazil’s fiscal difficulties have already pushed yields on inflation-linked bonds to around eight percentage points above inflation as measured by the IPCA index, creating “financial conditions that are choking the real economy.”
“One consequence is that mortgage rates, for example, which are based on long-term fixed income securities used to fund private banks, are already above 15% a year. Those monthly payments are beyond what the average Brazilian can afford. Property sales will fall, resulting in fewer new developments and less investment.”
Reflecting fiscal uncertainty and elevated interest rates, UBS has adopted a more defensive asset allocation strategy for Brazilian investors. Its recommendation for inflation-linked bonds has been lowered to neutral from overweight, while the average duration of these securities has been shortened to 5.5 years from 6.5 years.
Domestic fixed income—including floating-rate, fixed-rate and inflation-linked securities—remains at the core of portfolios. Brazilian equities retain a neutral rating.
Srour expects Brazil’s Central Bank to struggle to resume interest rate cuts even if economic activity slows, as the fiscal adjustment will fall short of delivering a decisive boost to credibility. Without corrective action, concerns about fiscal dominance could resurface.
She expects inflation forecasts in the Central Bank’s Focus survey to undergo further revisions. Annual inflation, as measured by the IPCA, could exceed 6% if the real fails to appreciate significantly or remains near current levels.
Other sources of inflationary pressure include El Niño, the implementation of tax reform and the abolition of the six-day workweek with one day off, which will lead to significant cost increases being passed on to consumers.
Srour does not rule out a recession in Brazil in 2027, an outcome she says “is becoming increasingly likely.”
This article was translated from Valor Econômico using an artificial intelligence tool under the supervision of the Valor International editorial team to ensure accuracy, clarity, and adherence to our editorial standards. Read our Editorial Principles.