Click, tap, and done, Apple Pay is convenient but in India faces unique challenges
Apple Pay arrived in India on September 30. It works just like it is supposed to work — seamlessly. On Wednesday morning, hundreds of thousands of Axis Bank users spent their Wednesday morning adding their cards into the Wallet app on their iPhone. Apple, meanwhile, gathered journalists, analysts and technologists to its office in Mumbai to demo how Pay would work in India and how it was different from all other modes of payments, including UPI. Not necessarily superior, not necessarily inferior. Just different. Apple wanted the world to see that in action.
But before I talk about the Apple Pay experience and take a look at India’s unique Fintech landscape that will challenge Apple in ways the US and European markets don’t, let me take a step back. Let us first talk about 2025.
In India, Apple Pay is coming nearly 12 years after it was first rolled out in the US. But behind this simple fact, there is a complex nuance that most people may not notice immediately. It is that even if Apple wanted, it would have been nearly impossible for the company to launch Apple Pay in India before April 1 this year.
India has been one of the first countries — and thank god for that — where credit and debit card transactions need a two-factor authentication, whether the transaction is done online or offline. It is a great way to minimise scams and fraud. A simple card swipe is not enough in India, putting in just the card details and CVV is not the only requirement. As per the Reserve Bank of India rules, payments here need two-factor authentication (2FA), either through an OTP or through a PIN. Apple Pay, meanwhile, does not work with an OTP or a PIN. The promise of Apple Pay is secure transactions but without any friction. Before April 1, 2026 it was largely incompatible with this RBI rule.
Before Apple Pay could roll out in India, RBI and Apple needed to be on the same page. It happened in the middle of 2025 when RBI issued a fresh circular on 2FA in online and offline transactions. The rule was modified to recognise newer, better, and more efficient ways to do secure transactions. 2FA continued to be mandatory, but now authentication through Face ID or Touch ID was given the same privilege that a SMS OTP or PIN would get. And thank god for that because this two-factor authentication is cryptographically and operationally more secure.
The change in rule, which went into effect from April 1, 2026 also meant that Apple Pay could finally arrive in India. On September 30 it did. Adding a card in Apple Pay is quite easy, though only one bank is supported at the moment.
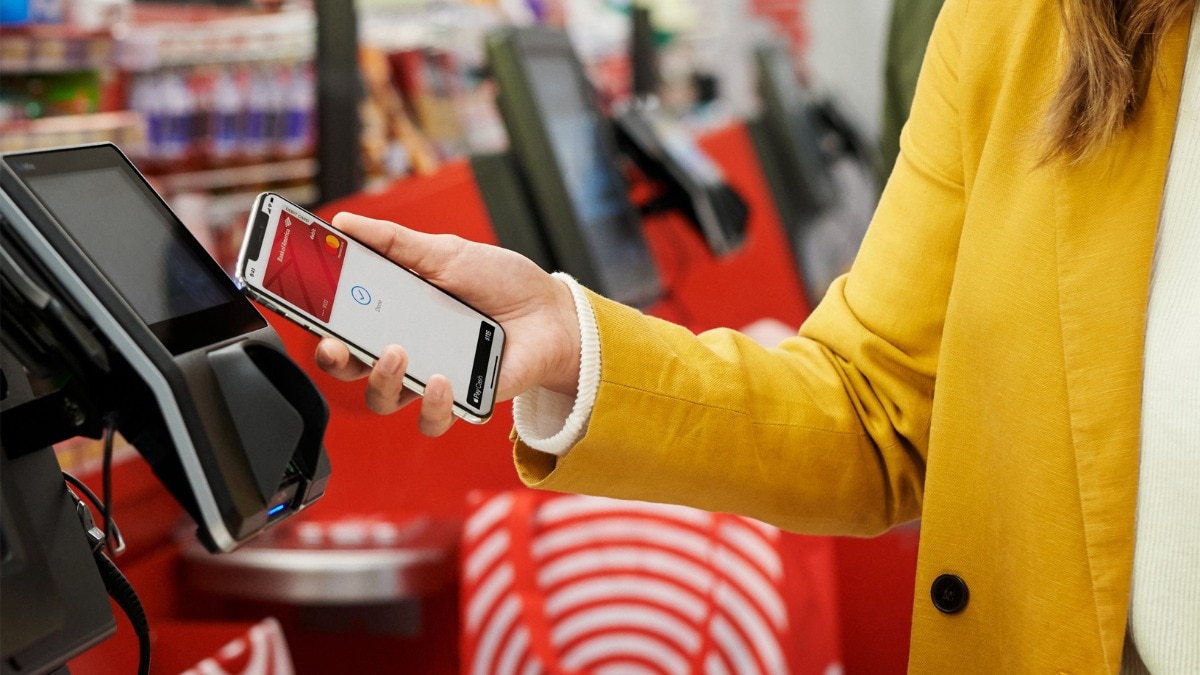
The experience of using Apple Pay in India is exactly the same as it is in other countries, including the US. Irrespective of the amount you are paying, whether it is Re 1 or Rs 1 lakh, you do not need an OTP or PIN to complete the payment. You just double click the side button on the iPhone, or on the Watch, and then tap the device to a card reader. The same happens with online payments, where you simply have to double click the side button on your phone and then look into its front camera. The two-factor authentication still happens, but now it happens with Face ID on an iPhone, and the wrist biometric signal on your Apple Watch.Seamless but limited in scope
As a number of people tried Apple Pay at the kiosks where Apple had set up the demo stations in its office, again and again there was one word they said — seamless. And this seamlessness, as it is typical of most Apple apps and services, starts from the very beginning.
Apple Pay in India currently supports credit and debits cards issued by Axis Bank. Also for now only Mastercard and Visa are supported. But if you happen to have a compatible Axis Bank card, and an iPhone, you can set up Apple Pay in a few minutes. You can add multiple cards in Apple Pay, as well as can change the default card.
Adding the card is easy. Open the Wallet app on the iPhone and simply select the option that will let you add a card. Once you are ready, place the card below the phone’s camera module. The phone, using Near Field Chip (NFC) in the iPhone, will read the card details and connect to your bank, for now Axis Bank, automatically. After that it is just a matter of adding the CVV number, and then one-time authentication using OTP.
Alternatively, users can also use the Axis Bank app to add their card to Apple Pay. Or do it manually by adding details in Wallet.
Apple says it cannot see the card number or other details on the phone, or in the cloud. Only users can because the data is cryptographically locked using a device-specific key. In fact, card details are not even transmitted to merchants when a payment is made. To make a payment you just need to tap your iPhone with the card reader.
When the card details have been authenticated in the Wallet app, Apple Pay generates a cryptographically secure unique device ID. It is this ID that is shared with the payment gateway when users make a payment. In other words, the device ID is like a virtual number for your actual credit or debit card number.
Once the setup is complete, and it takes just a few minutes, users can start making the payment. Apple says that almost all machines that support NFC payments — tap-to-pay feature — will be able to accept Apple Pay transactions. That is because these machines feature NFC, and hence users will be able to tap their phone or Watch to make the payment. Every payment will also need to be re-authenticated, which will happen through Face ID in the case of iPhone and biometric markers in the case of Apple Watch.
Online payments, however, need a bit more behind-the-scenes work. Support for Apple Pay needs to be built into an app or website. It needs to be added by developers. On September 30, Apple Pay launched with support from a number of online stores but the list is still small. Though some popular stores like Zomato, Blinkit, Nykaa, and Zepto are on board. Apple Pay is supported on multiple e-commerce sites and apps in India, including on Blinkit.
Apart from the seamlessness, the whole payment mechanism is fairly robust. As it has been a practice by Big Tech companies, Apple Pay is considered a sensitive technology and hence there are several layers of cryptography for its data. The data is encrypted with device-specific unique keys that are hardcoded in the hardware, and the actual details of the card are never stored in plain format. Apple also says it does not share transaction details with third-party entities for advertisement or any other reasons. In addition, Apple Pay can be locked or even wiped out using Find My app in case you lose an iPhone or Watch.Unique Indian challenges and that UPI factor
Now, as great as Apple Pay seems in theory and practice, it is clear that in India it is going to face unique challenges.
When it comes to digital payments, India has one of the most advanced ecosystems in the world. Apple Pay, when it was launched in 2014, was a service that aimed to make transactions seamless. And it was sorely needed in the US of 2014 because in that country — and many others in the world — digital transactions were either clunky or woefully insecure. So, Apple Pay solved some big problems for consumers.
But Indians, and more so in 2026, are used to a sophisticated and seamless digital transaction ecosystem. We have UPI, which works beautifully, and in our payment systems there is also a fairly robust 2-factor authentication mechanism. It is true that Apple Pay is smoother with its PIN and OTP-free way of working. But the difference is not huge between a UPI payment and the tap-and-pay mechanism of Apple Pay. The only part where I find Apple Pay superior is its privacy aspect, as well as its availability outside India. It minimises the transfer of personal information during a transaction, and it definitely reduces sharing of purchase details with third-party entities.
But at the same time, it is limiting. Currently, only one bank in India supports it — Axis Bank. There is a possibility that more banks will join the Apple Pay network, but there are also reports that banks aren’t keen on revenue sharing that Apple is seeking on transactions. It is believed that banks make around 0.50 per cent on each credit or debit card transaction. Apple wants 0.20 per cent of this from banks, whereas banks are arguing for 0.15 per cent or 0.10 per cent.
It is no wonder that Apple’s first partner in India is Axis Bank, and not HDFC Bank or ICICI Bank, the two big kahunas in the financial sector. Axis Bank is probably hoping to win from the buzz brand Apple creates for its cards, the kind of buzz the bigger banks might not need or find valuable enough at the moment.
Irrespective, unlike a regular product market where Apple can sell phones and computers directly to people, in the fintech market the company has to work in a regulatory space where formal and informal rules exist between various players. On top of that, India’s regulatory markets can be tricky to navigate given the kind of players one encounters in the space. Not only are there entrenched incumbents, there are also a number of government departments that can tug and pull various strings to keep things in a certain way.
Apple will have to eventually find a way to bring more banks to Apple Pay. It has a few aces up its sleeve. But it will have to play those cards well and hope that the regulatory environment doesn’t change drastically. Apple will also need to find a way to make Rupee cards work with Apple Pay. It’s doable because the company has supported local payment gateways in other countries and not just Mastercard and Visa. And finally, Apple may have to bring UPI to Apple Pay. Although, currently my impression is that the company is not in a hurry to add this support to Wallet. Instead, it is looking at Apple Pay as a complementary service to UPI and the one that, it hopes, will find favour with its customers that tend to be — on-the-whole — richer and partial to credit card usage.- EndsAlso Read | Apple Pay launched in India, here is how you can use it on your iPhoneAlso Read | Apple Pay will increase credit card use in India, but experts see no impact on iPhone pricesAlso Read | Banning social media in India for minors is needed but there are risks, experts say
Javed is the Technology Editor at India Today Group Digital. He has over two decades of experience covering consumer tech, gadgets, Big Tech, and AI. In 2014, he started India Today Tech and built it into one of India’s biggest technology news sites. Apart from keeping an eye on the intersection where tech, society, politics and economics meet, Javed writes a weekly newsletter -- This Week In AI. Good fiction, Wes Anderson, and a day in the wild photographing birds with his trusty Nikon Z8 are his preferred ways of digital detox.