PetroSA was owed R227m, but may end up losing R1.4bn instead - Daily Maverick
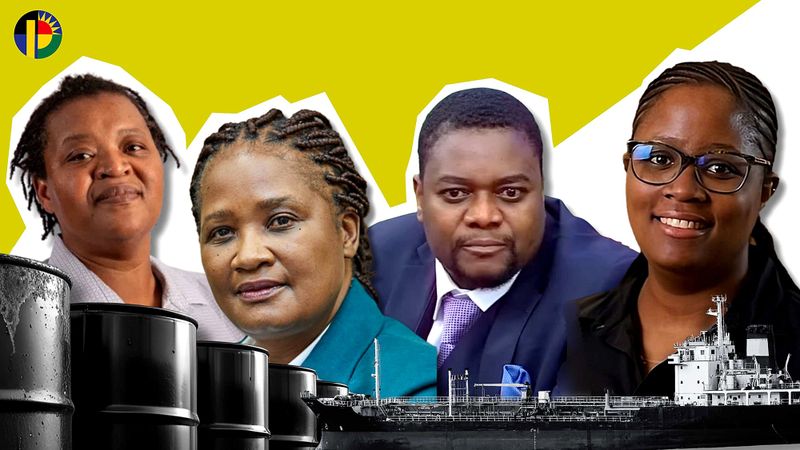
State-owned fuel company PetroSA faces liquidation after entering into a ludicrous settlement with an obscure but ambitious fuel trader, Nako Energy.
When state-owned fuel company PetroSA walked into the boardroom at its Parow head office, it was owed R227-million. By the time it walked out, it had agreed to a deal so toxic that it now faces the possibility of losing R1.4-billion instead – and potentially liquidation.
The meeting had been called in May 2025 to settle long-outstanding debts between PetroSA and a junior fuel trader, Nako Energy.
PetroSA owed Nako R605-million for a cargo of petrol it bought in June 2024, but had struggled to sell because it was tainted with a problematic chemical additive. Nako, in turn, owed PetroSA R832-million for a cargo of diesel it had bought and never paid for.
[Read AmaBhungane’s Dirty Fuels investigation, which covers the diesel deal in part 1 and the unleaded petrol deal in part 2.]
PetroSA should have had a R227-million upper hand, while Nako – whose claim to fame was largely its partnership with PetroSA – should have been grovelling.
Instead, Nako persuaded PetroSA to accept a new deal: PetroSA would buy another 11 cargoes of unleaded petrol from Nako and receive a discount of 45c per litre. Once PetroSA had sold 505 million litres of fuel, it would be R227-million richer, and Nako’s debt would – hey presto – be eliminated.
When PetroSA’s then interim CEO Sesakho Magadla appeared in Parliament last year, she said: “[W]e are both owed by Nako and we also owe Nako, and in us trying to find a solution – that balances what we need to do and also make sure that PetroSA does not suffer losses – both parties have agreed in terms of the acknowledgement of debt, in terms of the commercial settlement and also finalising the repayment plan.”
Yet the deal is far worse than it appears because once Nako had PetroSA’s signature on an acknowledgement of debt, it ceded the document to its lenders who were demanding to be paid for the same shipment of fuel.
This is a classic bait-and-switch: PetroSA thought it was negotiating with a trusted partner and that the two opposing debts would cancel each other out. Instead, its half of the debt was ceded to Nako’s creditors, whose lawyers soon came calling.
Now – with a letter of demand in one hand and a toxic petrol deal in the other – PetroSA is facing liquidation. A memo, apparently written by acting CEO Nombulelo Tyandela and sent to PetroSA staff over the weekend, said that Nako had approached the Western Cape Division of the High Court on Friday, 11 September, for “an order placing PetroSA under provisional liquidation”.
“PetroSA is considering the application and is obtaining the necessary legal advice,” a spokesperson confirmed on Wednesday. PetroSA’s last hope is that Parliament will pass the South African National Petroleum Company Bill, and roll all its debts into a new state-owned enterprise, funded by the taxpayer.
PetroSA declined to comment on the 59 detailed questions we sent to them over the past two weeks, and all emails and calls to Nako’s sleek Melrose office went unanswered.
This is the story of how PetroSA made a bad deal much worse.
(If you recall last year’s Dirty Fuels investigations, skip to Part 2: ‘Worst. Deal. Ever.’ If you want a recap, read on.)
PetroSA should have known better: in September 2022, a little-known fuel trader, Nako Energy, offered to sell PetroSA unleaded petrol at an unusually juicy price: 50c off the government-determined basic fuel price (BFP).
Fuel trading works on razor thin margins, and the other offers PetroSA received – from Glencore, Addax and Augusta – were uneconomical. But at BFP less 50c, Nako’s offer would generate a profit of R25-million for every vessel that landed in Mossel Bay.
“There’s 50 million litres [in a tanker], so PetroSA would make R25-million profit, which is higher than any diesel cargo. That’s when really the interest in Nako became bigger,” the company’s chair and majority shareholder, Nkosinathi Ngwenya, told us.
Yet as one experienced fuel trader told me, the first question PetroSA should have asked – when confronted with a deal that seemed too good to be true – was: What is in the fuel?
Instead, PetroSA agreed to a six-month trial with Nako Energy, which would automatically be renewed for another two years if things went well: a potential R11-billion deal that PetroSA hoped would help it capture the market for unleaded petrol on the Garden Route.
Within a month of Nako’s first cargo being delivered, customers at TotalEnergies and Caltex stations started complaining that the fuel was leaving stains on the paintwork of certain cars and motorbikes. By February 2024, complaints had arrived from Shell and Engen as well.
An internal PetroSA investigation would later conclude that the unleaded petrol “reacted to the car paint to the extent that these cars needed to be repainted. The [fuel] affected certain paints, and not all of them, and also seemed to affect older cars. This was confirmed by the panel beaters in Mossel Bay who treated a few of these cars that needed to be repainted.”
The Garden Route has a relatively small market for fuel. To save on costs, the oil majors share infrastructure and buy fuel from each other: “In Mossel Bay, the established arrangement is that the oil majors [had] supply agreements with PetroSA for all fuel products from its refinery, when it was operational. Currently, PetroSA supplies these companies using imported fuel,” Phila Mzamo, a spokesperson for the Fuels Industry Association, told us in 2025, adding that this was a “common practice in the fuel industry, known as a hospitality arrangement”.
What this means is that unbeknown to customers, many petrol stations on the Garden Route had sourced their fuel from PetroSA, who in turn had bought it from Nako.
Internal PetroSA tests would later establish that the fuel contained very high levels of N-methylaniline (NMA), a chemical additive that can boost the octane rating of a low-octane fuel, turning an 89 unleaded petrol into a 93 or 95.
“This particular blend was supposed to be a gamechanger,” PetroSA’s then head of trading Vusi Xaba told us when we interviewed him last year.
However, N-methylaniline is also toxic and can cause the build-up of gum in the fuel, which damages car engines. As a result, it’s banned as a fuel additive in Europe, China and Russia – but not South Africa.
By April 2024, Nako’s third cargo of unleaded petrol was on its way to South Africa: 50-million litres aboard a tanker called Daytona. But PetroSA was also facing a mutiny from its downstream customers who had pulled the fuel from their service stations.
“[B]oth Sasol and Astron Energy analysed the product and found in excess of 6% NMA,” Mzamo told us. “The NMA recommended rate is only around 1.2% – it is known above this level that gum formation is accelerated, and furthermore compatibility with other materials is brought into question.”
The problem is that N-methylaniline is not banned in South Africa, nor is it tested for, so technically the NMA-laced fuel can pass the South African National Standards tests without issue.
PetroSA was faced with a choice: accept a third cargo of Nako’s fuel and face the possibility that none of the oil majors would be willing to buy it. Or reject it – and face a legal fight with Nako.
The problem was that PetroSA had already agreed to make R150-million prepayments to Nako on each cargo, meaning that by April 2024, Nako had allegedly already been paid for a portion of the third cargo.
So PetroSA doubled down: it issued an “irrevocable and unconditional” payment undertaking to Nako, and its UAE-based supplier, Blue Ocean, promising to pay for the fuel within 30 days of it being delivered.
The fuel was delivered two months later, but two years on half the money remains outstanding and the payment undertaking PetroSA signed now threatens to bring the state-owned enterprise to its knees.
In April 2024, the cogs were already turning on another terrible deal for PetroSA.
PetroSA had ordered two cargoes of diesel from the Swiss trader Gunvor, that it hoped to sell to Eskom for its Gourikwa Open Cycle Gas Turbines, also outside Mossel Bay. However, there had been no load shedding since March, which meant that the turbines were not being used and PetroSA urgently needed to find another buyer for the diesel that was already waiting offshore.
Nako Energy should not have been PetroSA’s first choice, but for reasons that we unpacked in our first investigation, it agreed to sell 50-million litres of diesel to Nako at a R1.90/litre discount.
Nako’s CEO, Nqobani Mkhwanazi, told us that major oil companies were offering discounts of up to R1.80/litre at the time, adding: “An extra 10 cents is a good incentive. By no means is it preferential.”
So, by August 2024, PetroSA owed Nako R950-million for unleaded petrol and Nako owed PetroSA R933-million for diesel. And neither side was willing or able to pay.
Initially, Nako agreed to pay for the diesel cargo in R20-million/week instalments, but after four months, it stopped, citing PetroSA’s failure to pay for the unleaded petrol in return: “Nako has paid constantly, hoping that when we pay them, they’ll pay us for Daytona, but… nothing has ever come back to us,” Ngwenya, Nako’s chairperson, told us last year.
By the time amaBhungane published its Dirty Fuels investigation in May 2025, what may be the worst deal in PetroSA’s history of bad deals had already been signed.
On 19 May, just before our first exposé, Nako and PetroSA met to sign acknowledgments of debt: PetroSA agreed that it owed Nako R605-million while Nako agreed that it owed PetroSA R825-million.
But the acknowledgment of debt that Nako signed contained a caveat: “The payment for the abovementioned amount will be subject to a payment plan that will be developed and agreed upon by both parties no later than 31st May 2025.”
This was a terrible deal for PetroSA: it was handing over an iron-clad “irrevocable and unconditional” undertaking to pay Nako R605-million. In return, it would get its money but only through a yet-to-be-negotiated repayment plan.
That plan, signed a few days later, was mortifying: PetroSA agreed to honour the unleaded petrol deal, signed in 2023, which meant it would buy another 11 cargoes of fuel from Nako Energy at basic fuel price less 45c.
At current prices, the deal would cost PetroSA R7.4-billion. It would receive a 45c/litre margin, which after 505-million litres of petrol had been sold, would potentially produce R227-million in profit – the exact amount Nako owed if the two debts were offset.
This was a slightly worse deal than the 50c/litre margin Nako had originally offered, and seemingly amounted to PetroSA agreeing to write off the R227-million debt in exchange for keeping the original unleaded petrol deal alive.
It’s hard to see why any executive would want to pursue the original 2023 deal though: a year after receiving the Daytona’s cargo, more than half of the N-methylaniline-laced petrol was still sitting in PetroSA’s storage tanks in Mossel Bay. PetroSA had managed to sell small quantities: Nako had bought back roughly 3.7 million litres at a R1.35/litre discount and sold it to fuel stations in Gauteng. PetroSA had also moved at least eight truckloads to Bloemfontein – at a cost of R876,000 – so that the remaining fuel could be blended with untainted fuel.
In short, PetroSA had been trying to offload the chemically laced fuel for a year but had so far only managed to shift half a cargo (25 million litres).
Yet somehow, the executives at Nako – Ngwenya and Mkhwanazi, who had positioned themselves not just as suppliers but as trusted partners – had persuaded PetroSA that it would find a market for another 505 million litres.
Nako had apparently suggested that future cargoes could come from other suppliers, suggesting that these would not have contained the toxic fuel additive N-methylaniline, but PetroSA’s own sales data suggests it would have struggled to sell that volume regardless: between April and August 2025, it had sold just 16 million litres. The Nako deal required PetroSA to move 50 million litres every month.
Yet, when PetroSA’s acting CEO Sesakho Magadla had appeared in Parliament in June 2025, she defended PetroSA’s partnership with Nako: “From a PetroSA perspective, that partnership would have generated value and also changed the landscape for us to produce [unleaded petrol] competitively and also create value for us – and we are now being attacked.”
She added: “We’ve faced challenges. The contractual arrangements that we [have] make sure that both parties manage and mitigate against any further losses, that’s in line with contractual arrangements that are done by the industry.”
But if PetroSA thought it was negotiating with a trusted partner, the letter that arrived in August should have shattered that illusion.
Plane Tree Capital in Sandton describes itself as “bridging the gap between investors and borrowers”: it takes money from investors, and uses it to give loans, including to companies like Nako Energy.
In August 2023, Plane Tree had agreed to bankroll Nako’s unleaded petrol deal. It was risky: the buyer was PetroSA, a notorious state-owned enterprise with the track record of not paying its suppliers – it had closed out the 2023 financial year with R3.5-billion in unpaid trade payables.
The borrower, Nako, was seemingly no more reliable: when PetroSA asked Debtsource, a trade credit specialist, to review Nako’s credit worthiness, Debtsource gaven the company their lowest rating of “E”, which stood for “Unacceptable risk – recommend cash terms only. This category embraces customers who are financially weak and/or chronically unreliable in payment habits.”
Extracts from PetroSA emails suggest that by January 2024 the relationship between Nako and its lenders was already strained. Nako had delivered just two cargoes, and payment to Plane Tree on the second was seemingly already late.
“Yes the funds should be in the Nako account,” an unnamed Nako executive allegedly told Plane Tree in a Friday 26 January email. “I was sitting with CFO when she approved the payment on the system. It’s now up to the back office.”
By Monday, there was still no sign of the payment, and Plane Tree’s CEO, Richard Hart, was now irate: “This is now becoming an issue for us as we are once again at month end and this payment has still not been sent over. We have a number of clients awaiting funds and it is impossible for us to run our business with this lack of clarity. Please provide an update on when we can expect these funds,” he had supposedly written, according to an email extract.
Nako had forwarded Hart’s email to Tyandela, then PetroSA Group CFO, with a note to “humbly request an early payment for the cargo”, adding: “Our funders wish to close the book.”
Nako’s late payment hadn’t been enough to end the relationship with Plane Tree though, and when PetroSA agreed to accept a third cargo of unleaded petrol, Plane Tree seemingly put up the cash to pay Blue Ocean, the supplier in the UAE.
After a 108-day delay, the Daytona finally discharged 50 million litres of unleaded petrol in Mossel Bay on 17 June 2024. PetroSA had signed that “irrevocable and unconditional” payment undertaking and was supposed to pay Nako (and in turn Plane Tree) within 30 days, but this, after all, was PetroSA.
Two years later, Plane Tree is still waiting to be paid.
In June 2025, the PetroSA CEO, Magadla, had told Parliament that she was working with Nako to find an amicable solution – “to make sure that both parties manage and mitigate against any further losses”, she said.
In reality, though, Nako was working hard to protect its own interests: in August 2025, PetroSA received a letter informing it that Nako had ceded its debt book to Plane Tree Capital, and with it the “irrevocable and unconditional” payment undertaking (signed in April 2024) – which PetroSA had tried but failed to cancel – and the R605-million acknowledgment of debt (signed in May 2025).
What this meant is that Plane Tree now owned PetroSA’s debt, and could collect the full R605-million from PetroSA whenever it wanted – even though PetroSA had signed the acknowledgment of debt and agreed to take more petrol from Nako in the mistaken assumption that would be part of a broader settlement.
In fact, PetroSA and Nako had drafted an overarching settlement agreement that would have ensured that the two acknowledgments of debt were offset against each other. This would have left PetroSA in the comfortable position of being owed R227-million by Nako.
But before the settlement agreement could be signed, Nako had ceded its debt book to Plane Tree, and PetroSA had seemingly been outmanoeuvred.
In November 2025, Plane Tree’s attorneys, ENS, sent PetroSA a letter of demand – it now wanted R620-million plus interest: “Our client hereby demands immediate payment of R620,519,979 plus interest on this amount at the prescribed rate of interest from at least 20 May 2025 to date of final payment.”
Hart, the CEO of Plane Tree, declined to say how the R605-million debt had risen to R620-million. He did, however, confirm that as of September 2026, Plane Tree had not withdrawn the letter of demand: “This matter is subject to legal and commercial discussions with the parties involved. Accordingly, we do not wish to enter into public discussions about an ongoing matter,” he told us.
“As you have the contents of our letter, you have the basis for our claim against PetroSA. The letter of demand remains active.”
The cession of Nako’s debt to Plane Tree complicates things for PetroSA: Plane Tree has already demanded R620-million from PetroSA, and can bring an application to liquidate the state-owned fuel company tomorrow if it doesn’t pay.
PetroSA has, according to records we’ve seen, recently reduced its debt to Nako to below R500-million, but this is still more than PetroSA can probably afford to pay.
By comparison, if PetroSA wants to demand money from Nako, it must first find R7.4-billion to buy the agreed-upon 11 cargoes of fuel, then sell 505 million litres of petrol that likely no one wants to buy, just to reclaim a fraction of what it is owed.
Once the 11 cargoes have changed hands, PetroSA is entitled to claim the rest of its money, but because Plane Tree owns Nako’s debt book, it’s likely the Sandton lenders would have first dibs on any money currently in Nako’s bank account.
In short, if PetroSA wants to stay out of liquidation, it’ll probably first have to find the money to pay Plane Tree. And if Nako is no longer in business when the farcical petrol deal concludes, PetroSA risks losing its R832-million claim for the diesel it sold to Nako as well.
We put 59 detailed questions to PetroSA at the end of August and to its parent company, the Central Energy Fund, last week, but both ultimately decided not to comment.
From what we understand, officials have told the board that, in their view, Nako’s cession to Plane Tree “cannot be executed or implemented in any form or shape”, but internally, PetroSA was advised to get an urgent legal opinion to see where it stands.
On Monday, 14 September, amaBhungane received a memo, apparently written by Tyandela, who is now acting CEO, and circulated to staff over the weekend, informing them that Nako has brought an application to liquidate PetroSA.
“Management is mindful that news of the application may understandably cause concern and uncertainty among employees,” Tyandela apparently wrote. “Employees will be kept appropriately informed of material developments as the matter progresses. We ask colleagues to rely on official PetroSA communications and to refrain from speculation regarding the proceedings.”
Nako could not be reached for comment, while a spokesperson for PetroSA said: “PetroSA confirms that it has received a court application from Nako Energy in relation to the company. PetroSA is considering the application and is obtaining the necessary legal advice. The matter is before the Court and PetroSA will respond through the appropriate legal process.”
The one downside for Plane Tree – or anyone else seeking to liquidate PetroSA – is that the state-owned enterprise is already hopelessly broke: SARS is owed R4-billion and last year moved to seize the shuttered Mossel Bay refinery as collateral. PetroSA also owes more than R700-million to fuel trader Addax, according to leaked records we have seen.
But things are looking up for Plane Tree because Mineral and Petroleum Resources Minister Gwede Mantashe has asked Parliament to pass the South African National Petroleum Company (SANPC) Bill, which would merge PetroSA with three other state-owned companies: SANPC, the Strategic Fuel Fund and iGas.
If the bill is passed in its current form, both the debts and the assets of PetroSA would pass to the newly enlarged South African National Petroleum Company. But, as AmaBhungane has pointed out in a presentation to Parliament, the bill would also open the door for government bailouts.
“The Minister of Finance may, from time to time, approve advances and grants to the company… the Minister of Finance may approve special levies to provide funds for the Company…” section 26 of the bill reads.
Opposition parties are pushing back, though. Last month, in a rare show of unity, MPs from the DA, EFF, MK party and ATM backed a letter written by the DA’s James Lorimer, calling for debate on the bill to be stopped until PetroSA makes a full disclosure of its financial affairs.
“The fact that PetroSA has remained so opposed to revealing full details of its operations must on its own give rise to a suspicion of malfeasance or gross failure that is being concealed in order to save staff or officials from accountability,” Lorimer wrote in a letter read out by the chairperson of the Portfolio Committee on Mineral and Petroleum Resources, the ANC’s Mikateko Mahlaule.
On Tuesday 22 September, officials from the Department of Mineral and Petroleum Resources are scheduled to appear in Parliament to answer questions about the rapidly deteriorating state of PetroSA’s finances.
The main culprit on PetroSA’s balance sheet? Nako Energy. DM