
Value returns to China equities - The Business Times
THE recent volatility in US technology stocks serves as a reminder that, above all else, price matters. The artificial intelligence story remains intact; but after years of exceptional performance, much of the optimism is already reflected in valuations.
If the US sits at the top of the valuation spectrum, it is not an exaggeration to suggest that China sits near the bottom.
Valuations remain depressed; sentiment remains cautious; and many investors continue to focus on the challenges facing the Asian country’s property sector and broader economy, overlooking areas where earnings growth remains robust.
Beneath the headlines, a different investment story is emerging.
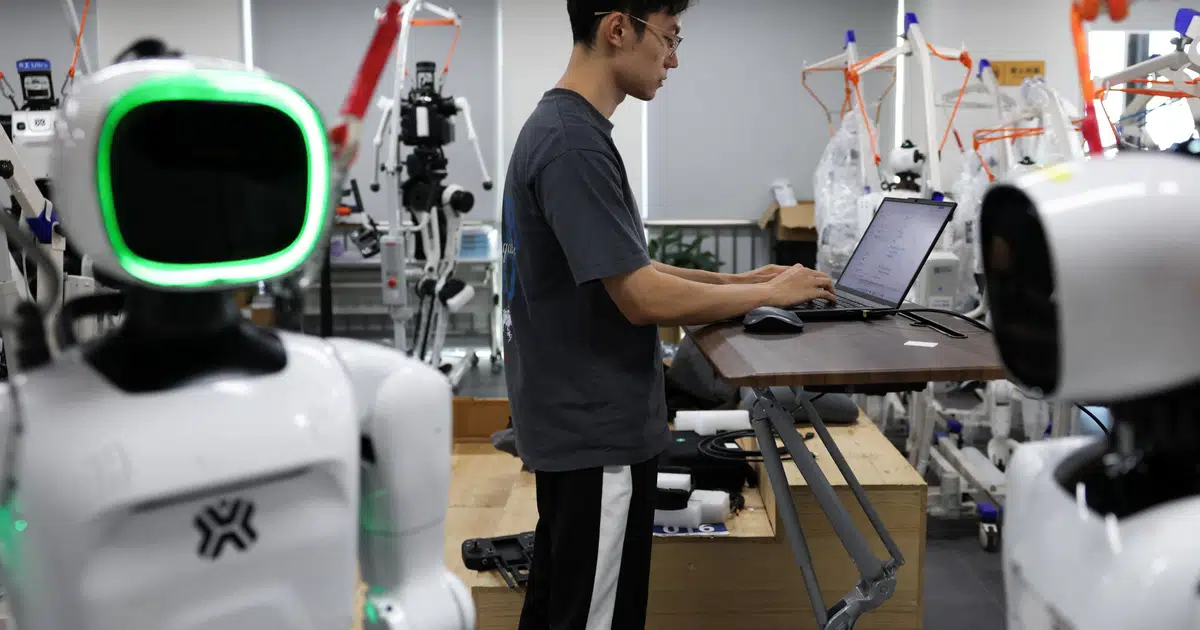
Some of China’s most dynamic companies are found in semiconductors, automation, AI, robotics and advanced manufacturing. These industries are becoming larger, more competitive, and increasingly important drivers of corporate profitability.
China’s equity market is increasingly reflecting the economy that the country is building, rather than the one it is leaving behind.
While economic headlines remain dominated by property weakness and subdued domestic demand, the market is increasingly rewarding sectors aligned with the country’s future development priorities.
Let me explain. The reason lies in the profound transition under way within China’s economy.
For decades, growth was driven by property development, infrastructure investment and expanding credit. That model delivered extraordinary gains, but it is now constrained by debt, demographics and diminishing returns on investment.
As that era matures, new sources of growth are gaining scale and importance. Industries at the forefront of technological innovation and industrial upgrading are becoming increasingly significant contributors to investment, productivity and corporate earnings.
While parts of the traditional economy continue to struggle, many of these sectors are strengthening their competitive position – both domestically and globally.
This matters because economies and equity markets do not always move together. Headline economic data remains weighed down by property weakness and subdued consumer confidence. Yet, a rising share of capital, profits and market returns is being generated elsewhere.
The key investment question is therefore not whether China’s traditional growth model is slowing. That is increasingly evident. The question is whether the country’s emerging growth industries can expand quickly enough to offset that drag. The answer remains open to debate.
Markets, however, are becoming more confident that they can. Many of the companies leading China’s technological transformation continue to deliver strong earnings growth while trading at substantial discounts to developed-market peers.
The result is a combination of innovation, productivity and value that has become increasingly difficult to find elsewhere.
We believe China’s transition can be accessed through three complementary themes: income, productivity and strategy.
China is increasingly becoming an income market. The country’s 10-year government bond yield recently fell to around 1.6 per cent, highlighting the limited return available from traditional fixed income.
Against that backdrop, many quasi-sovereign equities, including China Mobile, China Telecom, China Shenhua Energy, CNOOC and the major state-owned banks, offer dividend yields of between 5 and 8 per cent.
Investors can therefore earn several times the income available on sovereign bonds while retaining exposure to earnings growth and potential capital appreciation.
As property loses its appeal as a wealth-generation engine and bond yields remain exceptionally low, the incentive to reallocate savings towards income-producing equities continues to grow.
China’s long-term challenge is not simply slower growth. It is avoiding the fate that confronted Japan after its property and equity bubbles burst in the early 1990s.
While Japan’s broader economy endured a prolonged balance-sheet recession, some of its strongest-performing sectors were those that enhanced productivity, including factory automation, robotics and precision manufacturing.
China faces similar headwinds today: a property downturn, weak credit demand and an ageing population. The difference is that China enters this transition with a far more powerful productivity tool kit.
AI, semiconductors, robotics, industrial software and advanced manufacturing sit at the centre of China’s response. Companies linked to AI infrastructure, optical components, semiconductors and industrial automation are already delivering some of the strongest earnings growth in the market.
The investment case therefore extends well beyond technology. It is ultimately about whether productivity gains can help China navigate property deleveraging and demographic headwinds more successfully than economies that faced similar challenges previously.
Geopolitical competition with the US has transformed technological self-sufficiency from an economic ambition into a national priority. Semiconductors, advanced manufacturing, industrial technology, power equipment and AI infrastructure sit at the centre of this agenda.
These industries benefit from a powerful combination of policy support, capital allocation and long-term investment. China now accounts for roughly half of global industrial robot installations, produces more than 70 per cent of global electric vehicles, and has become the world’s largest market for renewable-energy equipment, battery technologies and power infrastructure.
Domestic semiconductor investment continues to run at tens of billions of dollars annually. For investors, this creates an unusual degree of earnings visibility. Demand is driven not only by commercial opportunity, but also by strategic priorities that are likely to persist well beyond a normal business cycle.
The debate around China is often framed through the lens of property weakness, debt and demographics. Those challenges are real, but they are also widely understood and increasingly reflected in valuations.
The more important question is whether investors are paying sufficient attention to the sectors where earnings, investment and competitive advantages continue to strengthen.
In the US, investors are debating whether AI has become too expensive. In China, investors can access many of the same structural themes at roughly half the market multiple while also earning significantly higher dividend yields.
Ultimately, the investment case is straightforward. Investors today can access attractive income, exposure to long-term productivity gains and sectors benefiting from powerful strategic tailwinds, all at a substantial discount to many global peers.
For Lombard Odier, that combination of value, income, productivity and strategic support justifies an overweight allocation to both onshore and offshore Chinese equities.
Higher rates, weaker spending: Is the Philippines entering stagflation?
